
E
R
T
A


Weekly Economic Bulletin 14.09.2026 - 18.09.2026
-
Published by
Erta Audit
-
Type
Bulletin
-
Date
September 21, 2026
-
Reference
Weekly Economic Bulletin 14.09.2026 - 18.09.2026
Weekly Economic Bulletin 14.09.2026 - 18.09.2026
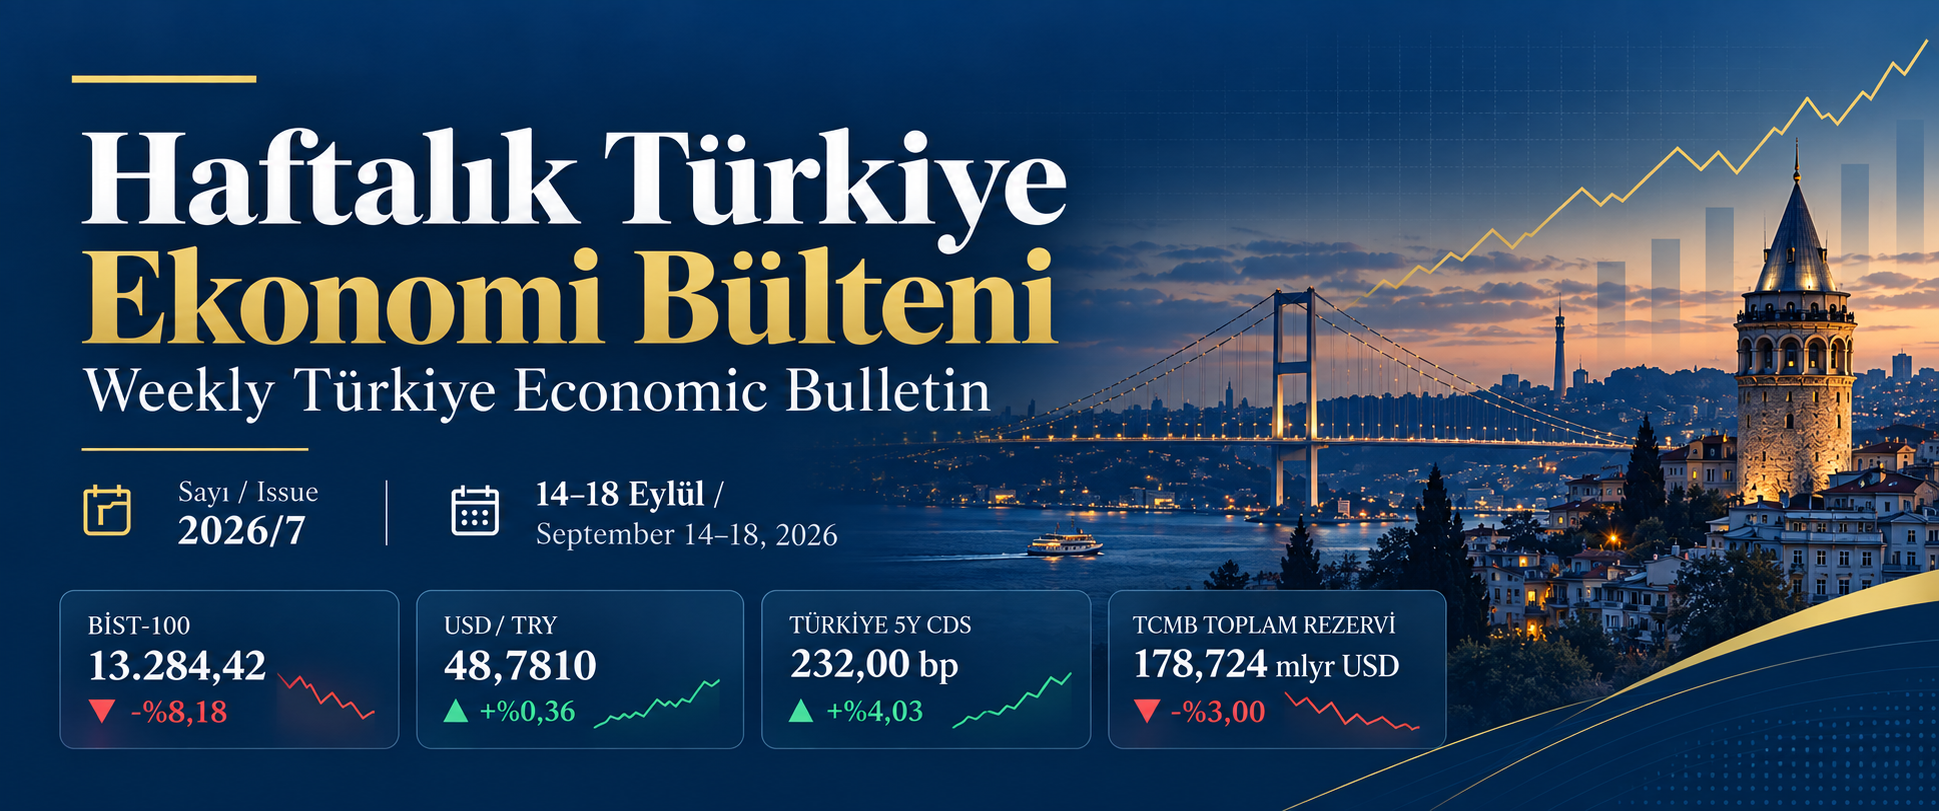
Weekly Türkiye Economic Bulletin
ISSUE 2026/7
Period covered: September 14–18, 2026 · Market close: Friday, September 18, 2026
Executive Summary
The BIST 100 ended the week at 13,284.42 points, down 8.18% from the previous Friday’s close; over the same week, Türkiye’s 5-year CDS rose from 223.02 basis points to 232.00 basis points. The sharp decline in the index, accompanied by a simultaneous deterioration in the risk premium, indicates that investors repriced Turkish assets over the course of the week.
The CBRT’s total reserves for the week of September 11, 2026 fell from USD 184.247 billion in the previous week to USD 178.724 billion (-USD 5.523 billion, -3.00%). Of the decline, USD 3.56 billion came from gold reserves and USD 1.96 billion from gross foreign-exchange reserves.
The U.S. Federal Reserve (Fed) raised its policy rate by 25 basis points on September 16, 2026, to a target range of 3.75%–4.00%; this marked the first rate increase since 2023. The decision coincided with the sell-off in Turkish lira assets during the same week.
On September 17, 2026, the Capital Markets Board of Türkiye (CMB) imposed a trading ban on TEFAS-traded funds managed by seven portfolio management companies and decided to liquidate 130 investment funds; during the same week, it was announced that Pusula Portföy, one of these companies, had defaulted on redemption payments for certain funds.
Market Dashboard
USD/TRY
48.7810
▲ +0.36%
Previous (Sep 11): 48.6057
EUR/TRY
55.9580
▼ -0.91%
Previous (Sep 11): 56.4722
BIST 100
13,284.42
▼ -8.18%
Previous (Sep 11): 14,467.90
CBRT POLICY RATE
37.00%
━ unchanged
No MPC meeting this week; latest decision: September 10, 2026
TÜRKİYE 5Y CDS
232.00 bp
▲ +4.03%
Previous (Sep 11): 223.02 bp
GRAM GOLD (24-KARAT, SELLING PRICE)
TRY 6,826.00
▼ -0.06%
Previous (Sep 11): TRY 6,830.10
CBRT TOTAL RESERVES
USD 178.724 bn
▼ -3.00%
Week of Sep 11; previous: USD 184.247 bn (week of Sep 4)
SOURCE NOTE
Weekly close-to-close changes in USD/TRY, EUR/TRY, the BIST 100 and gram gold were taken from Anadolu Agency’s weekly market-performance compilation; the gram-gold figure represents the selling price of 24-karat bullion and is compared using consecutive weekly observations from the same publisher (selling price versus selling price). For Türkiye’s 5-year CDS, the September 18 closing value was taken from İş Yatırım’s Eurobond Market report, while the September 11 closing value was taken from investing.com’s historical data table; because the comparison is based on two different approved providers, the weekly change should be read as an approximate magnitude. The CBRT’s total reserves equal the sum of gross foreign-exchange reserves (USD 68.444 billion, weekly change -USD 1.962 billion) and gold reserves (USD 110.28 billion, weekly change -USD 3.56 billion); these category-level weekly changes are also part of the same CBRT weekly reserve statistics. These weekly figures announced by the CBRT were compiled through approved secondary sources because of direct-access restrictions. The 2-year benchmark government bond and Brent crude were not included in the dashboard this week because no approved source simultaneously provided two comparable weekly closing values for both items.
Arrows and colors indicate only the weekly direction of each indicator: increase = green ▲, decrease = red ▼, no change = gray ━. Any assessment of whether a move is economically positive or negative is left to the accompanying text.
Official Indicators
TurkStat — Releases of September 14 and 17
In the foreign trade indices for July 2026 released by TurkStat on September 14, the terms of trade declined by 4 points to 91.3 from 95.3 in the previous month; the annual increase in the import unit value index (12.8%) exceeding the increase in the export unit value index (8.2%) is seen as a component of this deterioration in the terms of trade. In the August 2026 housing sales statistics released on September 17, total sales amounted to 127,410 units; first-hand sales fell by 4.5%, while second-hand sales declined by 19.4%. The share of mortgaged sales increased to 17.4% (22,131 units, +7.2%), while sales to foreigners remained limited at 1,938 units (1.5% share).
COMMENTARY The decline in housing sales being markedly deeper in the second-hand market than in first-hand sales shows that the two segments are being affected by different dynamics (credit costs, inventory, and price expectations); grouping them under a single heading of “housing demand weakened” risks overlooking this distinction between first-hand and second-hand sales.
CBRT — Releases of September 17
In the weekly money and banking statistics for the week of September 11, 2026, released by the CBRT on September 17, total deposits were reported at TRY 33,456.9 billion and M3 money supply at TRY 32,071.2 billion. In the weekly reserve data released on the same day, total reserves declined to USD 178.724 billion. In the securities statistics for the week of September 7–11, non-resident investors recorded net purchases of USD 277.7 million in equities and USD 151.2 million in Government Domestic Debt Securities (GDDS), while posting a net sale of USD 5.8 million in private-sector bonds; the combined components indicate a net inflow of USD 423.1 million.
COMMENTARY The fact that foreign investors remained net buyers of equities, when read together with the BIST 100’s 8.18% decline during the same week, indicates that the sell-off in the index was predominantly driven by resident investors; the two data sets do not contradict each other, but rather complement one another.
Ministry of Treasury and Finance, BRSA and CMB — Releases of September 15 and 17
In the August 2026 central government budget realizations released by the Ministry of Treasury and Finance on September 15, the budget recorded a TRY 12.9 billion surplus; the cumulative budget deficit for January–August reached TRY 1,308.1 billion. In two domestic borrowing auctions held on the same day (a 2-year fixed-coupon bond and a 4-year TLREF-indexed bond), total net sales amounted to TRY 83.3 billion. In the weekly banking-sector data announced by the Banking Regulation and Supervision Agency (BRSA) on September 17 (as of September 11), total loan volume rose by TRY 141.6 billion week-on-week to TRY 28,269.8 billion, while total deposits increased by TRY 307.7 billion to TRY 32,165.2 billion. During the same week, the Capital Markets Board of Türkiye (CMB) filed criminal complaints against 38 individuals on grounds of transaction-based market manipulation; it also imposed a trading ban on all TEFAS-traded funds managed by seven portfolio management companies, decided to liquidate 130 investment funds, and temporarily reduced the maintenance equity ratio for margin transactions to 20%.
COMMENTARY The overlap between the scope of the CMB measure (130 funds and seven portfolio management companies) and the redemption default involving one portfolio management company that became public during the same week reinforces the impression that the issue was not confined to a single company, but covered a group of funds and managers.
Table 1 — Official data released during the week (September 14–18, 2026)
Regulatory Calendar
SCOPE NOTE
No new regulation was identified in the Official Gazette issues published during the week of September 14–18, 2026 (Issues No. 33370–33374) in the areas of taxation, VAT, corporate/income tax, social security, Public Oversight Authority / TFRS-TMS, BRSA, CMB, Turkish Commercial Code, or independent audit.
Economic Agenda
Credit Ratings
This week, Moody’s, Fitch, S&P, Scope and JCR had no scheduled or unscheduled rating action concerning Türkiye. S&P’s next review is scheduled for October 16, while Scope’s next review is scheduled for October 23, 2026.
Foreign Investor Flows
According to the weekly securities statistics announced by the CBRT on September 17, non-resident investors made net purchases of USD 277.7 million in equities and USD 151.2 million in Government Domestic Debt Securities (GDDS) during the week of September 7–11, while recording a limited net sale of USD 5.8 million in private-sector bonds; the combined result of the three items corresponds to a net inflow of USD 423.1 million. Cumulative net purchases since the beginning of 2026 reached USD 4.34 billion.
Companies
Alves Kablo announced that it was unable to repay its TRY 100 million commercial paper at maturity. Pusula Portföy Yönetimi reported that it had defaulted on redemption payments for participation units in certain investment funds; the company was also subject to the CMB’s trading-ban decision during the same week. Meanwhile, demand for NETGL’s secondary public offering reached 2.8 times the offering size.
Global Backdrop
Following its September 15–16 meeting, the U.S. Federal Reserve (Fed) raised its policy rate by 25 basis points to a target range of 3.75%–4.00%; this was the first rate increase recorded since 2023. The European Central Bank (ECB) had no monetary policy meeting this week; its next meeting is scheduled for October 28–29, 2026. In a separate development, following Iran-related sanctions imposed by the U.S. Treasury Department’s Office of Foreign Assets Control (OFAC), Mahan Air announced that it would suspend its Türkiye flights from September 21.
Next Week’s Calendar
Table 2 — September 21–25, 2026
SENTENCE OF THE WEEK
“In weeks when an economy’s risk premium rises, the exchange rate, bond yields and equity prices generally move in the same direction, reinforcing one another.”
Sources
Primary sources (official institutions)
- TurkStat — Foreign Trade Indices, Housing Sales Statistics (tuik.gov.tr; compiled via secondary sources due to access restrictions)
- CBRT — Weekly Money and Banking, Reserve and Securities Statistics; MPC decision (tcmb.gov.tr; compiled via secondary sources due to access restrictions)
- Ministry of Treasury and Finance — Budget Realizations, Domestic Borrowing Auction Results (hmb.gov.tr; compiled via secondary sources due to access restrictions)
- BRSA — Weekly Banking Sector Data (bddk.org.tr; compiled via secondary sources due to access restrictions)
- Capital Markets Board of Türkiye (CMB) — Weekly Bulletin and Board Decisions (spk.gov.tr; compiled via secondary sources due to access restrictions)
- Federal Reserve (federalreserve.gov) — FOMC interest-rate decision
- European Central Bank (ecb.europa.eu) — meeting calendar
Secondary sources
- Anadolu Agency — weekly performance data for USD/TRY, EUR/TRY, BIST 100 and gram gold (approved secondary source)
- İş Yatırım — Türkiye 5-year CDS, September 18 close (approved secondary source)
- investing.com — Türkiye 5-year CDS, September 11 historical close (approved secondary source)
- HaberTürk — CBRT weekly reserve data (official data via a secondary channel due to access restrictions)
- Hibya News Agency — CBRT weekly money and banking statistics (official data via a secondary channel due to access restrictions)
- Borsametre — CBRT weekly securities statistics (official data via a secondary channel due to access restrictions)
- Finansopia — Ministry of Treasury and Finance budget and auction data (official data via a secondary channel due to access restrictions)
- Foreks / İş’te Mersin — BRSA weekly banking data (official data via a secondary channel due to access restrictions)
- Ahaber — CMB weekly bulletin decisions (official data via a secondary channel due to access restrictions)
- Karar, Ekonomist — TurkStat foreign trade and housing sales data (official data via a secondary channel due to access restrictions)
- Borsagündem — company news based on Public Disclosure Platform (KAP) filings
- Euronews Türkçe — report on Mahan Air flights
This bulletin is for general information purposes only and does not constitute professional advice for any transaction or decision. The data are based on announcements by official institutions and the sources specified above.
Muhsin GÜNYELİ
Sworn-in CPA · Independent Audit Partner